- Compare multiple quotes through specialist brokers
- Cover options for unusual construction and listed buildings
- Policies designed for specialist materials and rebuild risks
- Quick form to connect with experienced brokers
Non Standard Property Insurance
We partner with specialist insurance providers including
Why Use QuoteSearcher for Non-Standard Property Insurance?
Properties built using unusual materials or construction methods can be more difficult to insure through standard home insurance policies. Insurers may assess these buildings differently due to potential rebuild costs, maintenance requirements, or specialist repair work.
QuoteSearcher introduces property owners to brokers who regularly arrange insurance for non-standard properties. By completing a short form on our site, you can be connected with brokers who will review the construction type, age of the building and any specialist features before outlining suitable insurance options.
This approach lets you explore cover through brokers experienced in non-standard property risks, without needing to contact multiple insurers individually.

FINDING SPECIALIST QUOTES SINCE 2005
Online for over 20 years matching customers with specialist brokers

FAST AND SIMPLE PROCESS, YOU’RE IN THE RIGHT PLACE
Complete one simple form to receive multiple quotes, let us do the leg work for you

SIT BACK AND RELAX, YOU’RE IN CONTROL
You compare the quotes and choose the policy that best suits your needs
Customer's Love Our Service
Quick quote, no hassle and saved £700!
Fantastic can't fault in any way, would use time and again and recommend to all!
Excellent and fast service, will use again.
Quick helpful and cheap, can’t complain at anything. Thanks very much.
Found the site easy to use, had good feedback from four companies, all very competitive.
Helpful and efficient service, I was impressed how quickly I received my quotes.
Very quick responses and completed selection and purchase of a very competitive new policy within 24 hours.
Very good and easy to use, this has not only saved me money but also saved me a lot of phone calls and time, thank you.
Excellent service and delivered quicker than the website said. Have bought and will buy much more from here. Prices very competitive and often much cheaper. Yet to find something I want that they don't have.
Thought they were very good there was no need to ring around and I found what I was looking for.
What Is Non-Standard Property Insurance?
A property is generally considered non-standard when it’s built using materials or methods that differ from conventional brick walls and tiled roofs.
This may include properties with unusual structural elements, heritage features or specialist roofing materials. Because repairs and rebuilds may require specialist trades or materials, insurers often assess these buildings differently from standard homes.
Non-Standard Property Insurance Policy Features
Cover will vary depending on the property and insurer, but policies may include the following:
Building and Contents Cover
Protection for the structure of the property as well as internal fixtures, fittings and contents following insured events such as fire, flooding or storm damage. Find out more about Building and Contents Cover.
Structural Damage Cover
May include protection for issues such as subsidence, landslip or ground heave, depending on policy terms. Subsidence in particular can affect how insurers price and structure a policy, since it often involves ongoing monitoring or the property having been previously underpinned.
Damage from Fire, Weather or Vandalism
Cover for damage caused by fire, extreme weather, storms, or malicious acts.
Liability Cover
Property owners’ liability cover may assist with legal costs and compensation if a third party suffers injury or property damage connected to the property.
Types of Non-Standard Property Construction
Certain building methods are commonly classified as non-standard by insurers.
Non-Combustible Pre-Fabricated Homes
Often referred to as prefabricated or “prefab” properties, these homes are manufactured in sections off-site and assembled on location. While modern prefabricated homes can be large and complex structures, earlier examples may require specialist insurance due to their construction methods and materials.
Steel-Framed Properties
Steel frames offer strong structural support and are resistant to rot or decay. However, older steel-framed properties may contain materials such as asbestos insulation, which insurers may need to take into account when assessing risk.
Timber-Framed Properties
Timber-framed homes use a structural wooden frame rather than a solid brick internal structure. External walls may be finished with brick, stone, render or timber cladding, giving the appearance of a conventional home.
Wattle and Daub Construction
One of the oldest known building techniques, wattle and daub uses a timber framework filled with a mixture of mud, straw and other natural materials. Because repairs often require specialist methods and materials, insurance for these buildings is usually arranged through specialist brokers.
Underpinned Properties
A property that has previously subsided and been underpinned to stabilise its foundations is generally treated as non-standard, even once repairs are complete. Insurers may ask for details of the underpinning work and any warranties or guarantees provided at the time, and can take a more specialist approach to pricing and terms as a result.
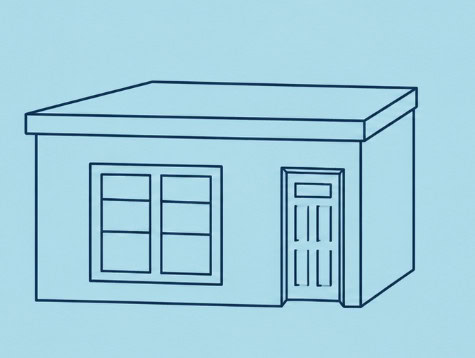
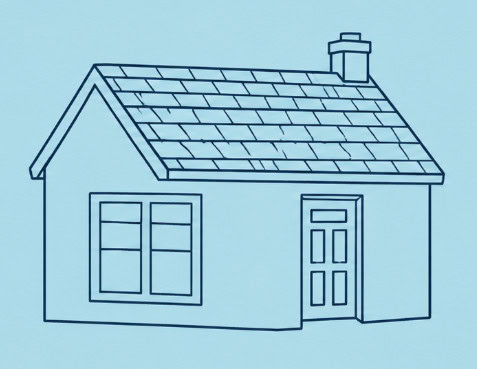
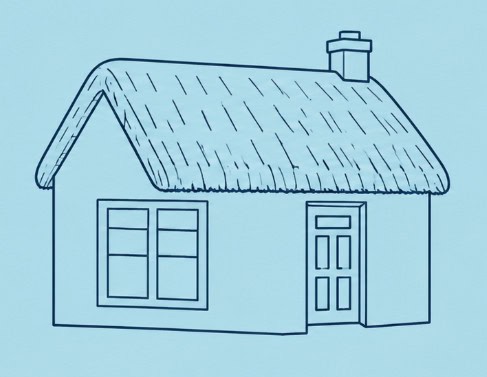
Non-Standard Roofing Types
Roof construction can also affect how insurers assess a property.
Listed Buildings and Heritage Properties
A listed building is one that appears on the UK Statutory List of Buildings of Architectural or Historic Interest. These properties are legally protected, and repairs or alterations usually require specific permissions.
Listed buildings are classified into three main categories:
- Grade I: buildings of exceptional historical or architectural importance
- Grade II*: particularly important buildings of more than special interest
- Grade II: buildings of special interest that should be preserved
Because repairs must often use traditional materials and specialist craftsmanship, rebuild costs for listed properties can be significantly higher than for standard buildings.
Non-Standard Properties and Landlords
If you’re insuring a non-standard property as a rental rather than your own home, this cover can usually be arranged alongside, or as part of, a landlord insurance policy. Brokers experienced in non-standard risk can talk you through how construction type, listed status or roofing material might affect a landlord policy specifically. Find out more about Landlord Insurance.
Properties that remain unoccupied for long periods may need separate unoccupied property insurance, while second homes may be better suited to holiday home insurance, depending on how the property is used.
Other Factors That Can Affect Non-Standard Property Insurance
Several factors may influence the availability and cost of insurance for non-standard properties:
- Unusual construction materials
- Specialist roofing types
- Property age
- Historic or listed building status
- High rebuild costs
- Environmental risks such as flooding, subsidence or previous underpinning
Properties that remain unoccupied for long periods may require separate unoccupied property insurance, while second homes or rental properties may need holiday home insurance or landlord insurance depending on how they are used.
FREQUENTLY ASKED QUESTIONS ABOUT NON STANDARD PROPERTY INSURANCE
Related Products
Unoccupied Property Insurance
Get Quotes
Holiday Home Insurance
Get Quotes
Landlord Insurance
Get Quotes